For millions of tenants, dogs are beloved members of the family. However, even the most well-behaved, gentle dogs can bite or scratch someone if they become startled, injured, or overly protective of their territory.
According to the Insurance Information Institute, dog bites and related canine injuries account for more than one-third of all homeowners and renters insurance liability claims payouts, costing hundreds of millions of dollars annually.
If you are a tenant with a dog, you are probably wondering: does renters insurance cover dog bites? The short answer is yes—standard renters insurance generally covers dog bites under its personal liability section, but there are massive exceptions, restricted breed lists, and specific policy limits you must understand to avoid being left unprotected.
Here is the definitive guide to how renters insurance handles dog bites, what is covered, and how to ensure you are fully protected.
1. The Core Answer: How Renters Insurance Responds to Dog Bites
A standard renters insurance policy (an HO-4 policy) is split into different types of coverage. When a dog bite occurs, two specific components of your policy are triggered to protect you financially: Personal Liability Coverage and Medical Payments to Others.
Personal Liability Coverage
If your dog bites a guest in your apartment or a stranger at a local park, and that person sues you for medical bills, lost wages, or pain and suffering, your Personal Liability coverage kicks in. It will pay for your legal defense (retaining an attorney to represent you) and cover the resulting settlement or court judgment up to your policy’s liability limits (typically starting at $100,000).
Medical Payments to Others
This is designed for minor, immediate incidents. If your dog nips a friend’s hand and they need to go to urgent care for a few stitches, Medical Payments coverage will pay those bills directly, usually up to a smaller limit (typically between $1,000 and $5,000). The benefit of this coverage is that it pays out regardless of legal fault, allowing you to handle small medical situations quickly before they escalate into formal lawsuits.
2. Where Does the Coverage Apply? (On vs. Off-Premises)
A common myth among tenants is that renters insurance only protects you inside the physical walls of your rented apartment or house.
In reality, renters liability insurance is worldwide coverage. If your policy covers your dog, that protection follows you and your dog wherever you go.
-
Inside Your Rental: If a delivery driver steps onto your porch or a maintenance worker enters your apartment and your dog bites them, you are covered.
-
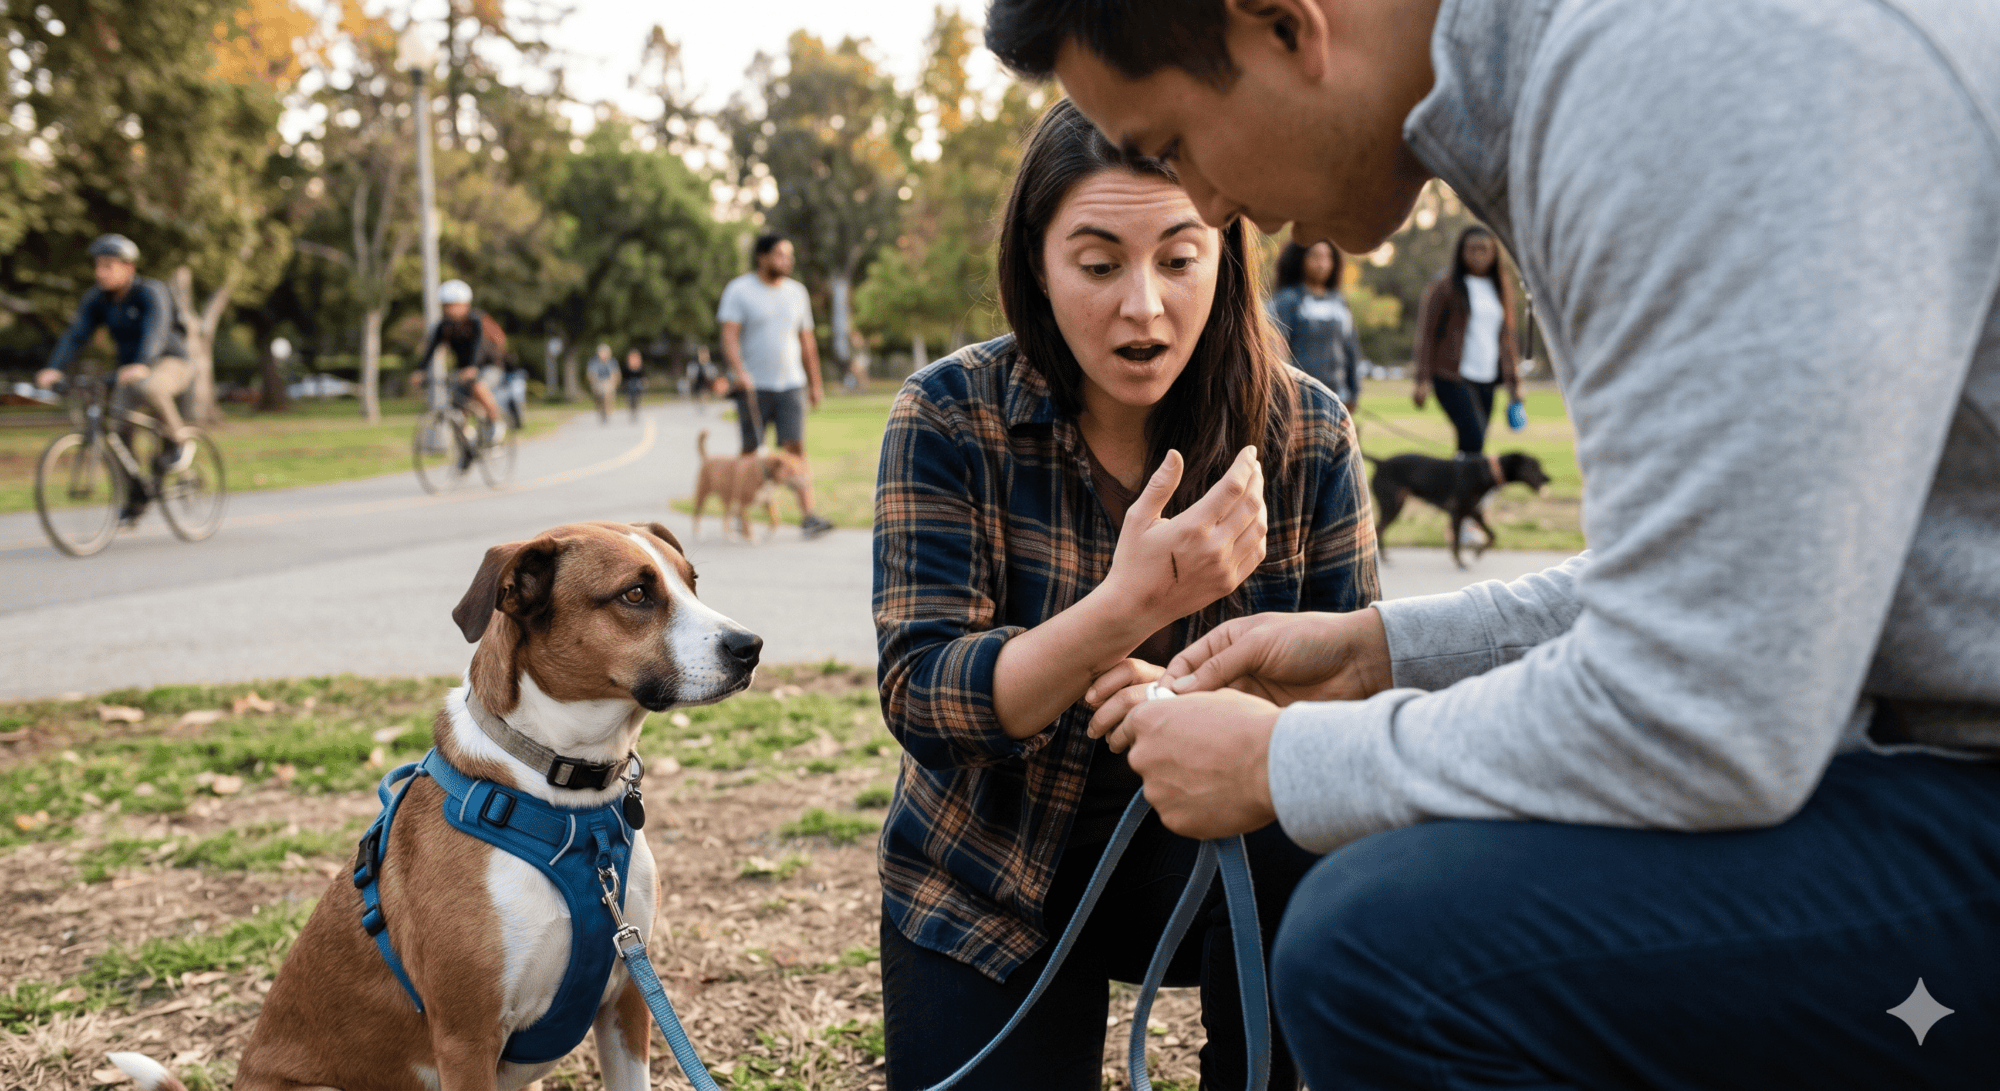
At the Dog Park: If your dog gets into a scuffle at a local park and bites another dog owner who tries to separate them, your liability coverage applies.
-
On a Walk or Vacation: If you are walking your dog down the street, or even traveling out of state, and an incident occurs, your renters insurance liability protection moves with you.
3. Crucial Exclusions: When Renters Insurance Will NOT Cover a Dog Bite
While standard policies offer robust protection, insurance companies are in the business of managing risk. There are several strict scenarios where an insurance carrier will deny a dog bite claim entirely.
1. The Restricted Breed List (The Dangerous Dog Exclusion)
Many insurance companies maintain a list of specific dog breeds they classify as “high-risk” or aggressive. If you own a breed on their restricted list, the company may refuse to issue you a policy, exclude dog liability entirely via a policy rider, or charge a much higher premium.
Commonly restricted breeds often include:
-
Pit Bull Terriers & Staffordshire Terriers
-
Rotweillers
-
Doberman Pinschers
-
German Shepherds
-
Chows Chows
-
Akitas
-
Wolf Hybrids
Pro Tip: Breed restrictions vary wildly by insurance carrier and by state law. Some insurance companies do not use breed lists at all, choosing instead to evaluate dogs on an individual behavioral basis.
2. The “One-Bite” Rule and History of Aggression
If your dog has an official history of biting someone or showing aggression, they are often classified as a “vicious animal” by underwriters. Once a dog has a known history of biting, a standard renters insurance policy will almost universally exclude any future canine liability. If your dog bites someone a second time, you will be entirely on your own for the legal and medical costs.
3. Injuries to Yourself or Your Household Members
Renters liability and medical payments coverage are strictly designed to cover other people (third parties). If your dog bites you, your spouse, your children, or anyone else listed as a resident on your policy, renters insurance will not pay a dime. Your personal health insurance is the only coverage that applies to injuries sustained by household residents.
4. What to Do If You Own a Restricted Breed or a Dog with a History
If you discover that your renters insurance carrier excludes your dog’s breed, or if your dog has a past history of aggression, you cannot simply go uninsured—the financial risk of a lawsuit is too high. You have two primary alternatives to secure protection:
Animal Liability Insurance (Specialized Standalone Policies)
Several specialty insurance companies offer standalone policies specifically designed to cover animal liability. These policies ignore breed restrictions and focus entirely on protecting you against dog bite lawsuits and third-party medical expenses.
Umbrella Insurance
If you own multiple assets or want protection that extends far beyond standard limits, a personal umbrella policy can provide an additional layer of liability coverage (typically starting at $1 million). However, you must ensure that the underlying renters policy does not have an outright canine exclusion, as an umbrella policy usually requires a baseline of primary coverage to attach to.
5. Steps to Take Immediately Following a Dog Bite Incident
If your dog bites someone, handling the situation calmly, responsibly, and systematically can drastically reduce your legal liability and ensure your insurance claim is approved smoothly.
-
Secure Your Dog: Immediately move your dog to a separate, secure room or crates to prevent further incidents and allow you to assist the victim safely.
-
Render First Aid: Help the victim wash the wound thoroughly with soap and warm water. Encourage them to seek professional medical attention, as dog bites carry a high risk of infection.
-
Exchange Information: Provide your name, contact information, and proof of your dog’s current rabies vaccination to the victim. Collect their contact details as well.
-
Gather Eyewitness Info: If anyone witnessed the incident, politely ask for their names and phone numbers. Their statements could be vital if there is a dispute over whether the dog was provoked.
-
Document Everything: Take photos of the location where the incident happened, any torn clothing, and the wound itself if possible. Write down a detailed narrative of exactly what happened while the memory is fresh.
-
Notify Your Insurance Company: Do not wait for a formal lawsuit to arrive. Contact your renters insurance provider right away to report the incident. Failing to report an incident promptly can give the carrier grounds to deny coverage later.
Summary for Tenants
Yes, renters insurance covers dog bites, making it an incredibly affordable way to protect your financial future as a pet owner. However, never assume your dog is automatically covered. Always review your policy’s fine print, disclose your dog’s exact breed honestly to your insurance provider to avoid claim denials for fraud, and ensure your liability limits are high enough to protect your assets.
More Reading on… What Does Renters Insurance Cover?
Does your policy actually say that?
Everything above is how renters policies generally work. Yours may read differently — carriers word coverage and exclusions their own way, and the endorsements you carry change the answer.
Send us your declarations page and we’ll read it and tell you, in plain language, what you actually have. If your coverage is already fine, we’ll tell you that too.
Have us review my policy — or email contact@insuredbyingram.com, or call (937) 741-5100.
Don’t have renters insurance yet? Get quotes in about three minutes — answer a few questions, set up your account, and see real rates from several carriers side by side.
Ingram Insurance Group — independent agency, 733 Salem Ave, Dayton, Ohio. No cost, no obligation.