
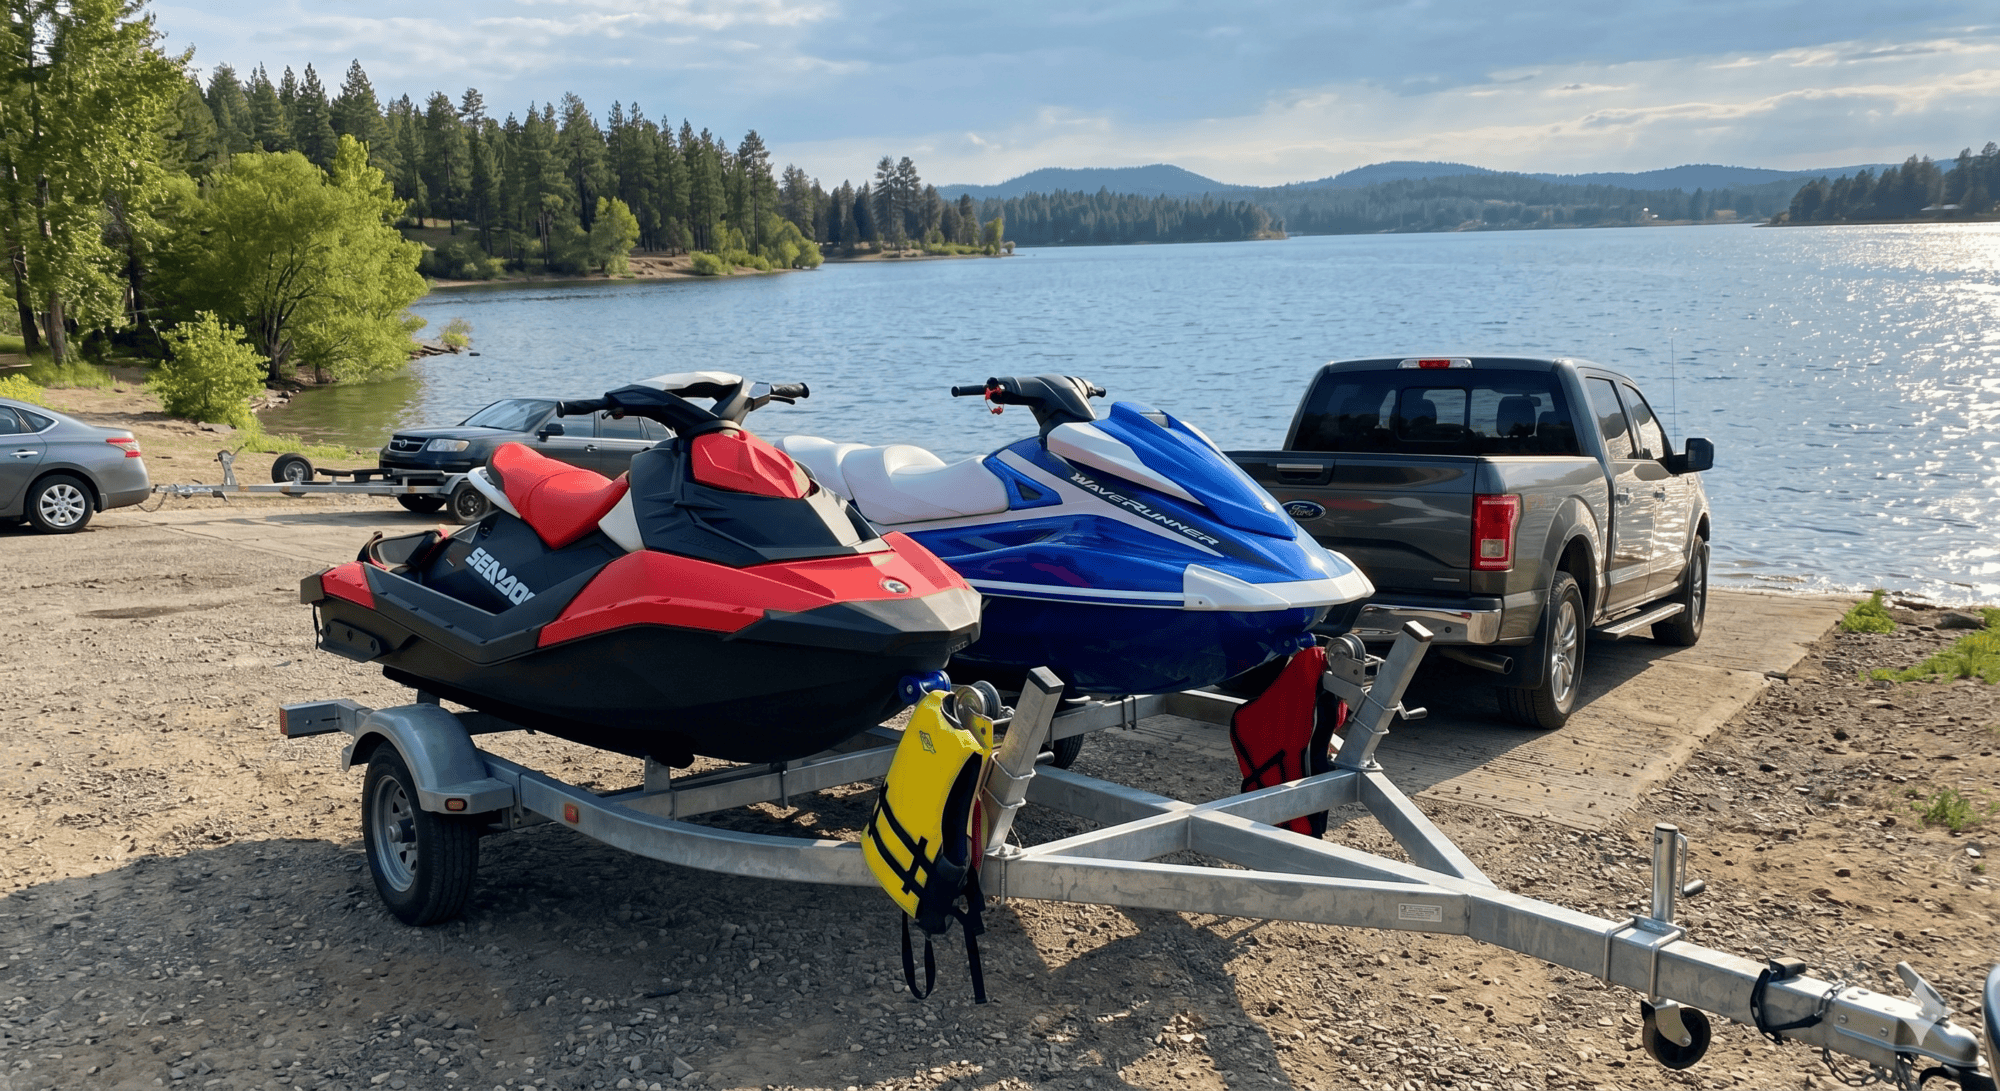
The Complete Jet Ski Insurance Buyers Guide: Costs, Coverages, & Legal Requirements
Whether you just hauled a brand-new Personal Watercraft (PWC) off the dealership lot or you are looking to protect an entire commercial fleet, managing your risks on the water is critical. Owning a jet ski brings unmatched speed, thrill, and agility to your weekends—but it also introduces unique liabilities and financial exposures that standard homeowners policies rarely touch.
If you are wondering about the legal realities, cost structures, and specific coverage mechanics of watercraft policies, this storefront guide covers everything you need to know.
1. Quick Quote Portal: Protect Your Watercraft Today
Before diving into the detailed policy breakdowns, you can get a customized, multi-state rate assessment right now. Tell us a bit about your watercraft to compare top-tier marine insurance carriers.
2. The Legalities: Do Jet Skis Need Insurance?
When assessing watercraft compliance, owners consistently ask: do jet skis need insurance by law? The answer is nuanced and depends primarily on your geographic location, your financing terms, and where you choose to launch your watercraft.
State-by-State Legal Requirements
Unlike automotive liability insurance, which is strictly mandated across almost every state, personal watercraft laws vary across the United States. For example, states like Arkansas and Utah have explicit liability insurance mandates for PWCs with engines exceeding certain horsepower thresholds.
However, even if your specific state does not legally require you to carry a policy, skipping coverage is highly risky.
Why “Not Legally Required” Doesn’t Mean Optional
So, do you have to have insurance for a jet ski if your state compliance office doesn’t force your hand? In practice, yes. You will almost certainly face mandatory insurance verification in the following common scenarios:
-
Financing and Lending Demands: If you finance your PWC through a bank, credit union, or manufacturer dealership, the lender will require a comprehensive marine policy to protect their collateral.
-
Marinas and Private Launches: Most public and private marinas, state parks, and high-end boat launches require proof of watercraft liability insurance before allowing you to drop your ski into the water or secure a slip.
If you are asking yourself, “do you have to insure a jet ski just to cruise around a local lake?” keep in mind that a single collision or dockside accident can expose your personal assets to devastating lawsuits.
+-----------------------------------------------------------------------+
|                       THE RISK RISK MITIGATION CHECKLIST              |
|                                                                       |
|  [ ] Legally required by state law?      --> Check local DNR statutes |
|  [ ] Required by lienholder/lender?     --> Mandatory if financed    |
|  [ ] Required by marina or boat ramp?   --> Most commercial facilities |
+-----------------------------------------------------------------------+
3. Demystifying Coverage: What Does Jet Ski Insurance Cover?
To understand the exact value of a dedicated marine policy, you must look beyond the premium costs and evaluate the underlying protections. A common point of confusion for new owners revolves around what does jet ski insurance cover when an incident occurs on open water or during highway transit.
A robust personal watercraft policy splits your protection into several core components:
Liability Coverage (Bodily Injury & Property Damage)
This is the foundational element of any watercraft policy. If you accidentally strike another vessel, a swimmer, a dock, or a navigating buoy, liability coverage pays for the third-party property repairs and medical treatments. It also funds your legal defense if an injured party files a lawsuit against you.
Comprehensive and Collision (Physical Damage)
-
Collision: Covers damage to your own jet ski resulting from an accident on the water, whether you collide with another PWC, a submerged log, or a rock formation.
-
Comprehensive: Protects your asset against non-collision hazards. This includes theft from your driveway, vandalism, fire damage, storm damage, and incidents that happen while your watercraft is securely sitting on its trailer.
Medical Payments (MedPay)
Water sports carry inherent physical risks. Medical payments coverage ensures that if you or your passengers are injured while riding, your initial medical bills, ambulance fees, and emergency room costs are covered, regardless of who caused the accident.
Specialized Marine Add-Ons
-
Wreck Removal: If a severe accident causes your jet ski to sink, local environmental and maritime authorities will require you to safely salvage and remove the vessel. This can easily cost thousands of dollars in specialized crane and dive fees. Marine policies include provisions to cover these recovery bills.
-
Fuel Spill Liability: Under federal and state environmental protection laws, leaking fuel or oil onto public waterways carries heavy financial penalties. This coverage handles the cleanup and remediation bills.
-
Watersport Medical: Extends your medical coverage to individuals being towed behind the PWC on wakeboards, tubes, or water skis.
4. Evaluating Your Risk: Do I Need Jet Ski Insurance?
If you are a safe rider who only hits the water two or three weekends a year, you might still wonder: do i need jet ski insurance, or can I skate by without it?
To determine whether a standalone policy is truly necessary for your lifestyle, let’s look at the limitations of standard consumer insurance lines.
The Homeowners Insurance Myth
A dangerous misconception among property owners is that an existing homeowners policy extends liability and physical damage coverage to personal watercraft.
Important Policy Note: While a standard homeowners policy might provide a small sliver of coverage ($1,000 to $1,500) for small, non-motorized watercraft like canoes, kayaks, or low-horsepower rowboats, it explicitly excludes high-performance, motorized personal watercraft like jet skis.
Why Horsepower Changes Everything
Modern jet skis frequently feature engines pushing anywhere from 60 to over 300 horsepower, capable of hitting speeds north of 60 mph in seconds. Because of this massive power-to-weight ratio, insurance underwriters classify PWCs as high-risk assets.
If you do not carry a dedicated marine policy, you face complete exposure to:
-
Total financial loss if your ski is stolen from your driveway or a hotel parking lot.
-
Out-of-pocket expenses for hull damage caused by submerged debris.
-
Personal financial liability for third-party bodily injuries that can quickly reach six figures.
When you carefully weigh the small price of a premium against the massive financial risks, asking “do you need jet ski insurance” is answered by a clear, resounding yes.
5. Cost Breakdown: How Much Does Jet Ski Insurance Cost?
For most owners, the ultimate deciding factor comes down to the bottom line: how much does jet ski insurance cost, and how can you secure the best possible value?
On average, a standard personal watercraft policy costs between $150 and $500 per year. However, because every rider and watercraft profile is completely unique, underwriters look at a wide range of rating variables to set your exact premium.
Core Variables Driving Your Premium
-
Engine Horsepower and Supercharging: A naturally aspirated touring model built for fuel efficiency costs significantly less to insure than a supercharged, race-ready muscle ski. Higher top speeds correlate directly with higher risk profiles.
-
Rider Age and Experience: Younger, inexperienced operators face higher premiums. Completing a certified state boater safety course can help offset this cost.
-
Hull Value and Make: A brand new, top-tier luxury PWC retailing for $20,000 will naturally cost more to cover for comprehensive and collision than a well-maintained, decade-old model worth $4,000.
-
Geographic Location: Insuring a jet ski in states with year-round riding seasons and frequent tropical storms (like Florida) will generally carry higher baseline rates than insuring a ski in northern states with shorter summer seasons (like Ohio or Michigan).
-
Deductible Structure: Choosing a higher out-of-pocket deductible (e.g., moving from $250 to $1,000) lowers your annual premium, though it means you shoulder more financial responsibility upfront during a claim.
6. Real-World Premium Cost Matrix
To give you a clearer picture of how these variables impact your wallet, the table below outlines typical annual premium ranges based on watercraft classifications and rider profiles.
Watercraft ClassificationExample ModelEstimated Annual PremiumTarget Rider ProfileRec-Lite / Entry-LevelSea-Doo Spark / Yamaha EX$150 – $250Casual riders, inland lakes, lower speedsStandard / RecreationYamaha VX / Sea-Doo GTI$250 – $400Families, weekend touring, moderate tow-sportsPerformance / LuxuryKawasaki Ultra 310 / Sea-Doo RXT-X$450 – $800+Experienced riders, coastal waters, supercharged enginesCommercial / Rental FleetCustom Fleet Multi-SkiCustom Commercial RatingRental operations, multi-state guided tours
7. Direct Search Variations: Answering Every Owner’s Core Question
When searching for the right coverage online, it’s easy to get lost in a sea of closely related questions. Whether you are typing how much is jet ski insurance, looking up how much is insurance on a jet ski, or running a quick search on how much is insurance for a jet ski, you are essentially looking for the exact same clarity: What is the fair market rate to protect my specific asset?
To give you direct, straightforward answers to these identical variations, we can break the costs down into predictable monthly and annual expectations:
-
How much is insurance for jet ski coverage on a monthly basis? For an entry-level to mid-tier watercraft with a clean operating record, you can expect to pay between $15 and $35 per month.
-
Does a jet ski need insurance if it is stored inside for the winter? Even when your ski is winterized and sitting in a garage, it remains exposed to risks like fire, theft, structure collapse, and rodent damage. Maintaining continuous comprehensive coverage year-round keeps your asset safe and protects any multi-policy discounts you have earned.
-
Do you need insurance for a jet ski if you are only riding on private lakes? While state law might not apply to completely landlocked private bodies of water, the physical risks of hitting a dock, sinking, or experiencing an electrical fire remain identical. Property owners’ associations also frequently mandate liability coverage for any watercraft launching on their private lakes.
8. Analyzing Your Specific Jet Ski Intent Questions
To make shopping for a policy as straightforward as possible, here is a quick reference guide addressing the exact questions riders ask when preparing their annual boating budgets:
Do you need insurance on a jet ski if it’s paid off?
Yes. Just like a car, paying off your loan eliminates the lender’s insurance requirement, but it does not eliminate your personal liability or the risk of losing your investment to theft or a sudden crash.
Do you have to have insurance on a jet ski when trailering it?
Your auto insurance policy typically extends liability protection to your trailer while it is hooked up to your truck or SUV. However, your auto policy will not cover physical damage to the jet ski sitting on top of that trailer if an accident happens on the highway. To protect the hull of the jet ski during transit, you need a dedicated watercraft policy.
Do you need jet ski insurance if you only ride as a passenger?
No. The insurance policy is tied directly to the owner and the specific watercraft vessel. If you are renting a ski or riding as a passenger on a friend’s PWC, you are typically covered by the owner’s primary liability policy, provided you have explicit permission to operate or ride the craft.
9. Commercial Needs: How Much Is Insurance for a Jet Ski Rental Business?
For entrepreneurs looking to capitalize on summer tourism markets, navigating the commercial insurance space is a completely different ballgame. If you are building a commercial fleet, you are likely asking: how much is insurance for a jet ski rental business?
The Commercial Risk Profile
Commercial operations face vastly higher premium costs than personal owners. When you rent high-speed personal watercraft to uncertified, inexperienced tourists, your liability profile sky-rockets.
Because of this, a personal watercraft policy will explicitly deny any claims if it is discovered that the vessel was rented out or used for commercial gain.
Key Factors for Commercial Fleet Quotes
To secure a commercial marine livery policy, insurers will analyze:
-
Safety Briefing Protocols: Do you require renters to watch instructional videos and complete temporary boater safety certifications before hitting the water?
-
Geographic Boundaries: Are your rental zones restricted to safe, supervised areas, or do renters have unrestricted access to open oceans or heavy commercial shipping lanes?
-
Fleet Size and Deductibles: Commercial operators routinely manage their premium overhead by carrying higher deductibles per vessel and utilizing multi-ski fleet discounts.
Commercial PWC rental insurance typically starts at $1,500 to $3,500+ per vessel annually, depending heavily on your location and safety record. For a precise commercial quote, business owners should work closely with a licensed marine specialty broker to build out a custom risk management package.
10. Maximizing Savings: How to Lower Your Jet Ski Insurance Costs
Protecting your watercraft shouldn’t have to break the bank. Insurance carriers offer a variety of standard discounts that can dramatically lower your annual premiums. When configuring your policy, ensure your agent applies all eligible credits:
-
The Boating Safety Course Discount: Completing an approved National Association of State Boating Law Administrators (NASBLA) safety course is one of the easiest ways to prove you are a responsible operator and secure an immediate premium reduction.
-
Multi-Policy Bundling: If you insure your home, auto, or primary boat with the same carrier, bundling your PWC policy can shave 10% to 20% off your overall bill.
-
Multi-Watercraft Credits: Insuring two or more jet skis on a single policy is highly cost-effective, as underwriters offer deep discounts for family fleets.
-
Clean Record Discounts: Maintaining a clean driving record on land and on the water tells underwriters you are a low-risk client, qualifying you for preferred tier rating structures.
11. Final Checklist: Securing the Perfect Marine Policy
Before you sign on the dotted line and launch your jet ski this season, take a quick moment to verify your coverage details against this storefront summary table:
+----------------------------------------------------------------------------+
|                        PWC INSURANCE VERIFICATION MATRIX                   |
+----------------------------------------------------------------------------+
| COVERAGE ELEMENT      | WHAT IT SECURES             | SHOULD YOU ADD IT?   |
+----------------------------------------------------------------------------+
| Liability             | Third-party injury/damage   | MANDATORY (All Riders) |
| Comprehensive         | Theft, storm, trailer fire  | RECOMMENDED          |
| Medical Payments      | Emergency medical bills     | RECOMMENDED          |
| Fuel Spill Clean-up   | Environmental penalties     | CRITICAL ADD-ON      |
| Roadside Assistance   | Trailer breakdowns on highway| OPTIONAL             |
+----------------------------------------------------------------------------+
Protecting your time on the water is all about eliminating financial uncertainty so you can focus on the ride. By working with a dedicated, independent agency that understands the subtle nuances of marine risks across multiple states, you ensure your family, your assets, and your financial future are fully protected against any storm.
12. Get an Instant Personalized Quote
Ready to see exactly how affordable premium coverage can be for your personal watercraft? Don’t leave your personal liability to chance this season. Fill out our streamlined digital application to compare competitive, customized rates from the industry’s leading marine insurers.
Does your policy actually say that?
Everything above is how these policies generally work. Yours may read differently — carriers word coverage and exclusions their own way, and the endorsements you carry change the answer.
Send us your declarations page and we’ll read it and tell you, in plain language, what you actually have. If your coverage is already fine, we’ll tell you that too.
Have us review my policy — or email contact@insuredbyingram.com, or call (937) 741-5100.
Ingram Insurance Group — independent agency, 733 Salem Ave, Dayton, Ohio. No cost, no obligation.





