
Clark County Ohio Homeowners Insurance: Full Local Risk & Coverage Analysis
Clark County sits at a crossroads of urban, small-town, and rural Ohio, with housing that ranges from 19th-century Springfield neighborhoods to mid-century subdivisions and farm-adjacent homes along the county’s outer edges. For homeowners, this mixture of aging infrastructure, severe weather exposure, and varied fire protection creates a complex risk landscape that generic insurance advice rarely addresses well. This analysis examines how Clark County’s built environment, weather patterns, and housing characteristics influence homeowners insurance, and outlines the coverage decisions local residents cannot afford to treat as routine. If you own a home in Springfield, Enon, New Carlisle, or the surrounding townships, understanding these dynamics is essential to structuring an insurance program that truly reflects your risk.
For broader regional context or comparisons with nearby suburban markets, you may also find it useful to review our guides on Centerville, Ohio homeowners insurance and Washington Township homeowners insurance, which highlight similar themes of aging roofs, basement water exposure, and underinsurance risks in nearby communities.
Meet Clark County, Ohio
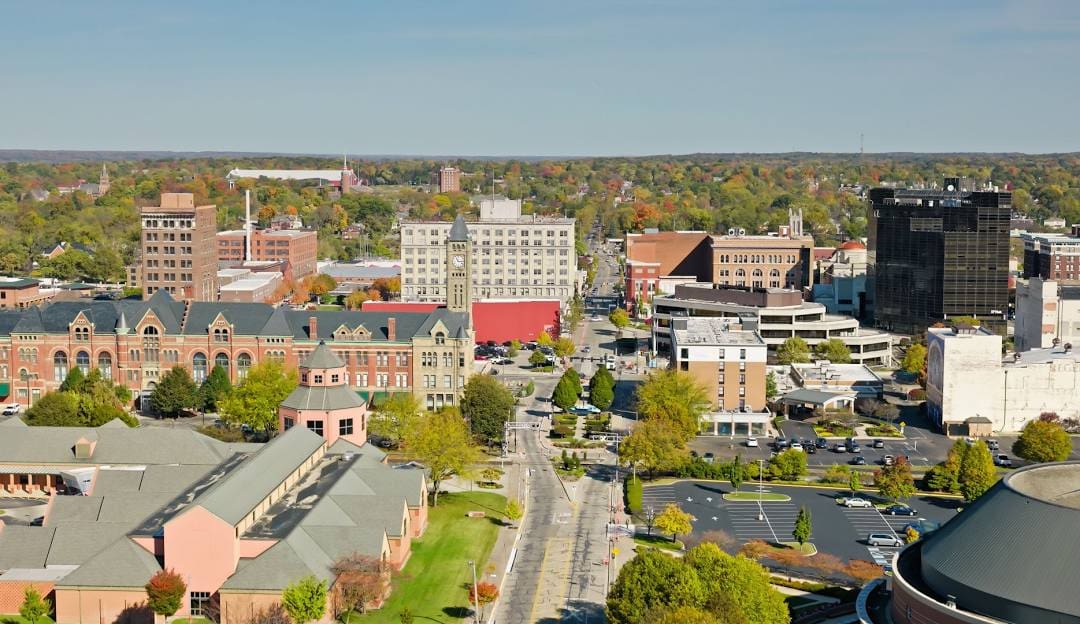
Clark County’s housing fabric reflects more than a century of regional development. The county’s core population center is the City of Springfield, whose older neighborhoods include late-1800s and early-1900s homes with brick or stone foundations, plaster interiors, steep roofs, and sometimes mixed or partially updated mechanical systems. Surrounding Springfield, communities such as Enon, New Carlisle, South Vienna, North Hampton, and the townships contain a blend of mid-20th-century ranches and two-story homes, manufactured housing, and more recent construction on larger lots.
This mix creates three broad residential profiles that matter for homeowners insurance in Clark County:
-
Historic and early-20th-century homes in Springfield: often characterized by aging roofs, original or partially updated wiring and plumbing, and basements with moisture or seepage histories.
-
Mid-century subdivisions and small-town grids: frequently built between the 1940s and 1970s, with cinder block or poured concrete foundations, older drain lines, and roofs approaching or surpassing expected service life.
-
Rural and exurban homes in the townships: properties on larger parcels, often with wells, septic systems, outbuildings, and more distance from fire stations, which affects both hazard severity and response times.
Across all three profiles, Clark County is subject to the same regional weather systems that impact Montgomery and Greene Counties: severe thunderstorms, convective wind events, hail, snow and ice storms, and periodic heavy rainfall that strains stormwater and sewer infrastructure. To understand homeowners insurance in Clark County, it is necessary to examine how these environmental forces interact with the county’s housing stock and infrastructure.
How the Built Environment Shapes Risk in Clark County
Insurance underwriters do not evaluate homes in isolation; they evaluate houses in the context of their surrounding environment, construction era, and infrastructure. In Clark County, several recurring built-environment patterns exert significant influence on risk scoring and coverage terms.
Older Springfield Neighborhoods
In many of Springfield’s older neighborhoods, homes may have:
-
Stone, brick, or early poured concrete foundations with limited or no modern waterproofing
-
Steep roofs with complex geometry, including intersecting gables and dormers
-
Plaster walls and original millwork that raise reconstruction costs
-
Mixed electrical systems, where original wiring coexists with later upgrades
These attributes matter because they increase both the likelihood and the cost of certain types of losses. For example, older foundations in areas with higher water tables or limited drainage capacity are more susceptible to seepage and hydrostatic pressure, particularly during extended rain events. Complex roofs are more vulnerable to wind uplift and ice dam formation. Historic finishes escalate the cost of repairing even relatively contained fire or water damage.
Subdivisions, Small Towns, and Edge Development
Mid-century portions of Springfield, as well as areas of Enon, New Carlisle, and similar communities, often include housing built with cost-efficient methods and materials common at the time of construction. These homes may feature:
-
Cinder block or poured concrete foundations without comprehensive perimeter drainage
-
Galvanized or cast-iron plumbing lines approaching end-of-life conditions
-
Service panels and wiring that predate current code expectations
-
Roofs that are 20 or more years old, sometimes with ventilation or flashing deficiencies
In these settings, plumbing failures, sewer backups, and roof leaks are recurring sources of homeowners claims. Some of the same issues appear in Dayton-area suburbs, and we examined them more closely in our discussion of sewer backup coverage in Dayton and Centerville, which applies conceptually to Clark County as well.
Rural and Township Properties
Clark County’s townships and outlying areas introduce additional variables. Rural homes often have:
-
Private wells and septic systems, which carry distinct contamination and failure risks
-
Outbuildings such as barns, workshops, or detached garages, each requiring appropriate coverage
-
Greater distances from fire stations and hydrant networks, increasing potential fire severity
-
Tree lines and open fields that shape wind exposure and storm behavior
For homeowners insurance purposes, these properties tend to require more attention to detached structure coverage, liability exposures (e.g., ponds, farm equipment access, or recreational land use), and adequate dwelling limits in the event of a total loss with extended rebuild times.
Weather & Storm Risks in Clark County
Like much of west-central Ohio, Clark County experiences a range of storm and weather events that can significantly impact homes. These do not affect all parts of the county equally, but some broad patterns are worth noting.
Wind and Hail Exposure
Clark County sits along regional storm tracks that often follow the I-70 corridor. Severe thunderstorms can produce strong straight-line winds, downbursts, and hail capable of damaging roofing systems, siding, exterior trim, and windows. Older roofs with brittle shingles, improperly fastened materials, or deferred maintenance are more likely to suffer damage in such events. Hail impact may not always be immediately obvious, but over time can accelerate roof deterioration and leak development.
Heavy Rainfall, Drainage, and Basement Water
Springfield’s older neighborhoods and some small-town grids were designed in an era before modern stormwater engineering practices. In these areas, heavy rainfall can lead to surface runoff concentrating along foundations, in alleys or rear yard low points, and in combined sewer lines. Basements with aging foundations and minimal waterproofing are at particular risk for seepage, dampness, or outright water intrusion.
It is critical to distinguish between different water-related causes of loss, because insurance policies treat them differently. Groundwater seepage or hydrostatic pressure is usually excluded from standard homeowners policies. By contrast, water that backs up through sewers or drains, or overflows from a sump pump, may be insurable if the homeowner has added a specific water backup endorsement. We explore this distinction in more detail in our Dayton-area discussion of sewer and sump backup coverage, and the same logic applies in Clark County.
Snow, Ice, and Tree-Related Losses
Winter storms create additional hazards. Accumulated snow and ice can stress older roofs, and freeze–thaw cycles encourage ice dams at eaves, especially on poorly ventilated or under-insulated roofs. Ice loading on trees can cause limb failures that damage roofs, porches, or power lines. In heavily treed streets and rural properties alike, these events can result in a combination of property damage and temporary loss of utilities.
Key Insurance Risks for Clark County Homeowners
Considering the built environment and weather patterns together, several recurring insurance risks emerge as especially important for Clark County homeowners.
Roof Age, Condition, and Coverage Limitations
Roofs are among the most critical components in homeowners insurance underwriting. Older roofs in Clark County, particularly those in Springfield and mid-century subdivisions, can trigger stricter insurance terms, including:
-
Higher wind and hail deductibles
-
Requirements for photographic evidence or inspection reports
-
Limitations to actual cash value (ACV) settlements on roof claims rather than full replacement cost
Homeowners should understand whether their policy provides replacement cost coverage on the roof or only ACV. Under ACV, age and wear are deducted, leaving the homeowner with a larger share of the replacement cost. In communities with older roofs, this can materially affect the financial outcome after a storm.
Basement Water and Sewer Backup
In many Clark County homes, especially in older Springfield neighborhoods and older small-town grids, basements are vulnerable to water intrusion. The distinction between excluded seepage and insurable water backup is vital. A water backup endorsement is often relatively inexpensive compared to the cost of even a modest basement water loss once demolition, drying, and repair are factored in.
Homeowners should review their policies to determine whether water backup coverage is present, at what limit, and whether sump pump failures are explicitly addressed. Those with finished basements, laundry rooms, or mechanical systems below grade should consider higher limits commensurate with the potential cost of replacing flooring, drywall, and equipment.
Underinsurance and Rising Rebuild Costs
In many parts of Clark County, the market value of a home does not accurately reflect the cost to rebuild it after a total loss. Historic Springfield homes, in particular, may have sale prices well below their full reconstruction cost because buyers are paying for an existing structure, not commissioning new construction. Meanwhile, building materials and labor costs have risen significantly in recent years.
Policies based on outdated or market-oriented dwelling limits risk leaving homeowners underinsured. A major fire or tornado loss could exceed the policy’s dwelling limit, forcing the homeowner to make up the difference. To mitigate this risk, Clark County residents should ensure their policies use realistic replacement cost estimates and consider endorsements such as:
-
Extended dwelling coverage (e.g., 25–50% above the base dwelling limit)
-
Guaranteed replacement cost where available
-
Inflation guard provisions that adjust coverage each year
Rural Exposures: Outbuildings, Wells, Septic, and Liability
In Clark County’s townships, homeowners often have additional exposures related to wells, septic systems, ponds, and detached structures. Standard policies may not automatically provide sufficient coverage for large outbuildings, workshops, or hobby-farm structures. Similarly, wells and septic systems can be expensive to repair or replace if contaminated or damaged. Liability exposures may also be higher where ponds, trails, or informal recreational use of land occurs.
Homeowners in these areas should verify that Coverage B (other structures) limits adequately reflect the value of their outbuildings, and that liability limits are sufficient given the nature of their property. For many households, this means considering liability limits of $300,000 or higher, and in some cases layering a personal umbrella policy on top.
How Homeowners Insurance Works in Ohio (Clark County Context)
Most owner-occupied homes in Clark County are insured on an HO-3 or comparable special form policy, which typically provides:
-
Coverage A – Dwelling: the main structure
-
Coverage B – Other Structures: garages, sheds, fences, etc.
-
Coverage C – Personal Property: belongings inside the home
-
Coverage D – Loss of Use: additional living expenses if the home is uninhabitable due to a covered loss
-
Coverage E – Personal Liability: protection against claims for bodily injury or property damage to others
-
Coverage F – Medical Payments to Others: limited no-fault medical coverage for guests
The HO-3 form generally provides “open perils” coverage for the dwelling, meaning it covers all causes of loss not specifically excluded, while personal property is covered on a named-perils basis. However, key exclusions—such as flood, earth movement, routine wear and tear, and water seepage—must be understood clearly. In Clark County, flood risk may be moderate compared to riverine communities, but localized flooding, sewer backup, and foundation water are prevalent enough to warrant careful attention to exclusions and endorsements.
Ohio policies also frequently employ percentage-based deductibles for wind and hail, particularly in regions with higher storm frequency. For a Clark County homeowner with a $300,000 dwelling limit and a 2% wind/hail deductible, this means a $6,000 out-of-pocket cost before insurance pays for storm damage. Choosing deductible levels, therefore, is not simply a matter of premium savings; it is a question of how much risk the household is prepared to retain.
For homeowners wanting a deeper grounding in broader Ohio insurance mechanics, including replacement cost versus ACV, our statewide analysis at Ingram Insurance provides additional context that complements this Clark County-specific focus.
Coverage Decisions Clark County Residents Should Examine Closely
Replacement Cost vs. Actual Cash Value
As noted, the decision between replacement cost and ACV has significant implications. In Clark County, where many roofs and structural elements are older, the depreciation deduction inherent in ACV can dramatically reduce claim payments. Replacement cost coverage on the dwelling often costs more in premium but functions as an important hedge against the financial consequences of a major event, particularly for historic Springfield homes and higher-value properties in certain townships.
Water Backup Endorsements
Given Clark County’s mix of older sewer infrastructure and basement-prone housing, water backup coverage is frequently a critical addition rather than an optional luxury. Homeowners should review endorsements to confirm:
-
Whether both sewer/drain backup and sump pump overflow are included
-
The dollar limit for any single water backup event
-
Whether coverage includes limited mold remediation
For many households, modest increases in annual premium can secure coverage limits that substantially reduce the financial impact of a basement water event.
Ordinance or Law Coverage
Code upgrade coverage is another area that can be overlooked. When a Clark County home is damaged, rebuilding is often subject to current building, electrical, and energy codes rather than the standards in place when the home was constructed. Features such as arc-fault breakers, GFCI outlets, or insulation standards may be required. Ordinance or law coverage helps pay for these upgrades, which are not technically part of the original loss but are required by law.
In older Springfield neighborhoods, where original construction may predate modern codes by decades, ordinance or law coverage can be particularly important in a major loss scenario.
Liability Limits and Rural Exposures
Homeowners in both urban and rural parts of Clark County should carefully evaluate their liability limits. Slips and falls on icy steps, dog-related incidents, injuries on recreational land, and accidents involving outbuildings or home-based activities can all give rise to liability claims. Selecting liability limits that align with household assets and income is a key component of a comprehensive homeowners insurance strategy.
Illustrative Scenarios from Clark County
Scenario 1: Wind Damage to an Aging Roof in Springfield
A Springfield homeowner with a 22-year-old asphalt shingle roof experiences a summer thunderstorm with strong winds. Shingles are torn away, and rain infiltrates the attic and upper floor. The homeowner’s policy includes ACV coverage for the roof, subject to a 2% wind/hail deductible. After depreciation and the deductible, the claim payment covers only a fraction of the full replacement cost. Had replacement cost coverage been in place with an adequate dwelling limit, the financial outcome would have been considerably different.
Scenario 2: Sewer Backup into a Finished Basement
In a small town within Clark County, a family has finished their basement with carpet, drywall, and a home office. A series of intense storms overloads local sewer capacity, and water enters the basement through a floor drain. Cleanup and restoration costs total $14,000. Because the homeowners had previously added a water backup endorsement with a $15,000 limit, the loss is largely covered, aside from their deductible. Without this endorsement, the entire cost would have been borne by the family.
Scenario 3: Fire and Code Upgrades in an Older Home
An older Springfield home experiences a kitchen fire that spreads into adjacent walls and ceiling cavities. The damaged portion of the home is reparable, but the local building department requires that the electrical system in affected areas be upgraded to current code. Ordinance or law coverage within the homeowners policy pays for the difference between replacing only what was damaged and performing the required upgrades, preventing a significant unexpected out-of-pocket expense.
Managing Premiums While Maintaining Adequate Protection
Although Clark County presents real weather and infrastructure-related risks, homeowners retain meaningful control over both coverage design and premium levels. Practical strategies include:
-
Replacing older roofs proactively with high-quality materials and proper ventilation
-
Updating electrical panels and correcting outdated wiring
-
Maintaining gutters, downspouts, grading, and sump systems to reduce water exposure
-
Installing monitored security and fire detection systems to qualify for discounts
-
Selecting deductibles that balance affordability with realistic loss scenarios
-
Bundling home and auto policies with the same carrier where appropriate
These steps can improve both insurability and premium competitiveness, particularly in homes that might otherwise be considered borderline or higher risk due to age or condition.
When and How to Review Your Policy if You Own a Home in Clark County
Because both property conditions and market factors change over time, Clark County homeowners should treat insurance as an ongoing process rather than a one-time transaction. Situations that should prompt a policy review include:
-
Completion of major renovations or system upgrades (roof, electrical, plumbing, HVAC)
-
Finishing or remodeling a basement or attic
-
Constructing or significantly improving detached structures
-
Substantial changes in local property values or construction costs
-
After severe weather seasons or a claim event
During such reviews, it is wise to revisit dwelling limits, endorsements (such as water backup and ordinance coverage), liability limits, and deductibles to ensure they remain aligned with both the property’s characteristics and the household’s financial resilience.
Working with a Local Independent Agent Who Understands Clark County
Because Clark County’s risk profile is shaped by a specific combination of historic housing, small-town grids, and rural properties, homeowners benefit from working with an insurance professional who understands these local nuances. A knowledgeable independent agent can translate technical underwriting considerations into clear choices, help calibrate coverage to both urban and rural exposures, and identify carrier options that are comfortable writing older homes, mixed mechanical systems, and rural properties.
Ingram Insurance is based in the Dayton region and routinely works with homeowners throughout Clark, Montgomery, Greene, and surrounding counties. Our familiarity with local housing characteristics, weather patterns, and claims histories allows us to design coverage strategies that reflect real-world risk rather than generic assumptions.
If you own a home in Clark County or are considering purchasing one, and would like a second opinion on your current policy or help structuring a new one, we are available to assist. Call Ingram Insurance at (937) 741-5100, email contact@insuredbyingram.com, or visit https://www.insuredbyingram.com/ to get started.





